

What Happened?
The Federal Reserve left interest rates unchanged during the March meeting. In their Summary of Economic Projections, they revised growth and inflation higher, tracking the data we have seen year-to-date. Importantly, the median dot for interest rates in 2024 remained unchanged, despite the higher growth and inflation estimates.
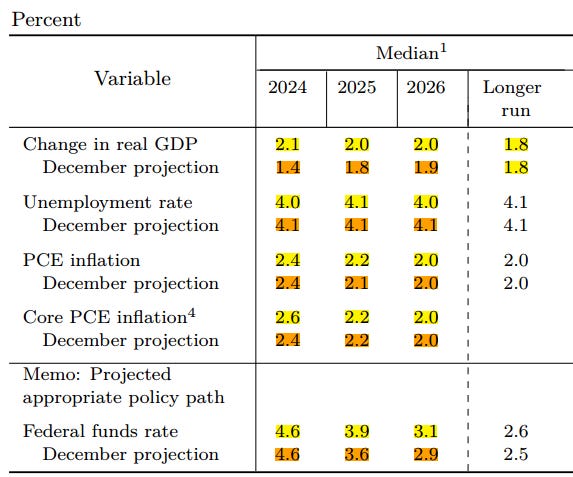
In our February letter, we express our view that the FOMC meeting would not be a significant repricing event, as the Fed would remain cautious. We’re glad to see this play out.
Overall, the SEP indicates the Fed’s desire to achieve a soft-landing; they do not seem willing to “break” something to reach their 2% inflation target. This is a good thing for the economy.
Market Response
The yield curve steepened, led by the front end. Markets had begun to price fewer cuts into 2024 -- remember, the year began with over 7 cuts being priced in; prior to the FOMC the market had narrowed that down to ~2.8 cuts. With the Fed reiterating their patience, 3 cuts are back on the table.
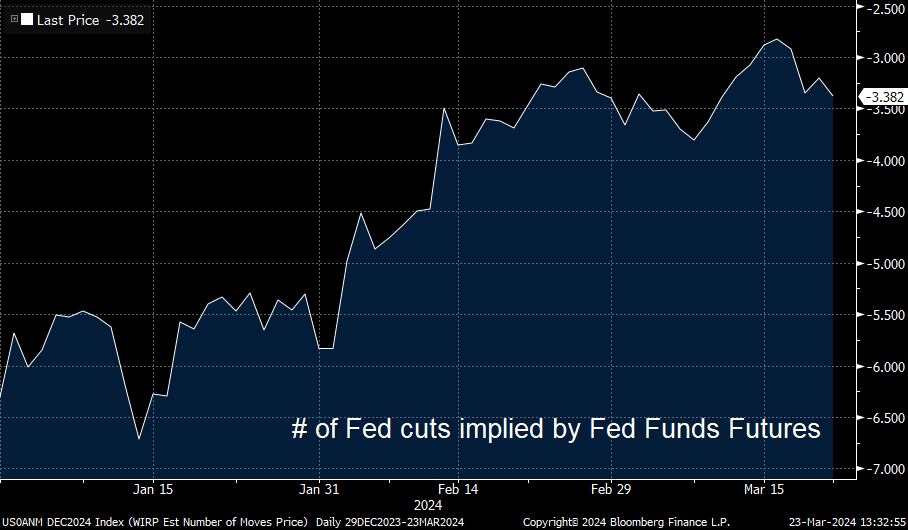
The stock market rallied modestly — investor positioning was marginally hawkish, expecting under 3 cuts.
Our View
We think mid-February marked the peak in strong economic data for 2024. We estimate economic growth will end the year around 1.5% which is quite below current estimates of 2.1% (2.1% is also the median estimate in the Fed's SEP).
Our view is based upon (a) interest rates that will keep non-residential fixed investment subdued, (b) a marginally softer labor market and consumer backdrop, and (c) declining fiscal support.
As the US economy trends towards a 1.5% growth rate, we currently see a 2-year yield above 3.5% to be "restrictive" to interest-rate sensitive sectors. We're not calling for a recession -- just a slower grind through the 2H of the year. This changes if the Fed, and other central banks, shift towards a more dovish policy stance.
What about the stock market?
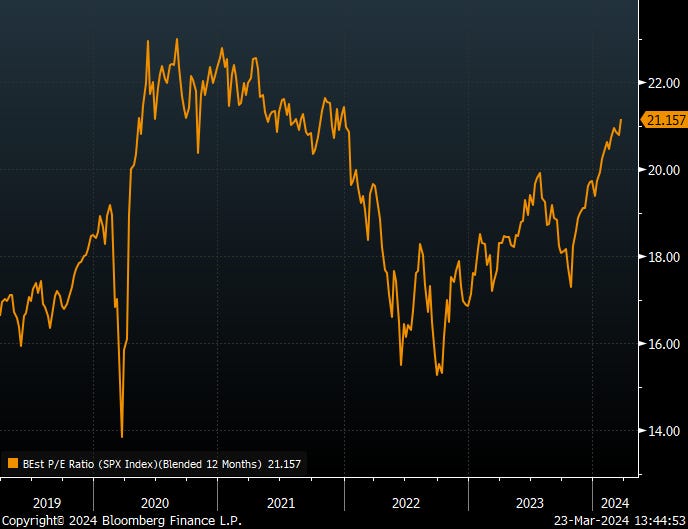
We are revising our price target on the S&P 500 up to 5300 from 5000, based upon 20.5x NTM EPS of $260. Driving our forecast is an SPX sales estimate that is too low given the level of NGDP growth expected this year, and that an improving margin dynamic, primarily among larger cap companies, will add further to the upside. Fed patience gives us more confidence that the soft landing we are in will persist.
If you have any questions, want to share insights, or chat, please don’t hesitate to reach out to us.
Muhammad Wahdy
Portfolio Manager
Wahdy Capital
Learn More | Schedule a Call | Investor Letters