

A quick update on what seems to be an election result favoring Donald Trump:
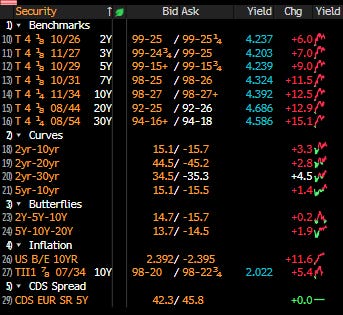
Treasuries are being sold: 2Y (+7.1bp), 10Y (+13.1bp), 10s-2s spread widening (+3.6bp)
Rate cut odds are shifting: 1.6 cuts by Dec 2024, 4.3 cuts by Dec 2025
Risk assets are being bid: Bitcoin (+7.22%), S&P Futures (+1.85%), Nasdaq Futures (+1.73%)
In our prior note we wrote:
Investors should trim duration exposure in front of a potential Trump victory. This is because policies stated by Trump imply a higher R-Star (neutral rate of interest) with higher risk of inflation, which is bad for the growth factor and duration.
This largely seems to be panning out with the Russell outperforming Nasdaq and the long end selling off vs. short end. But what does the performance differentials of these assets mean for a portfolio moving forward?
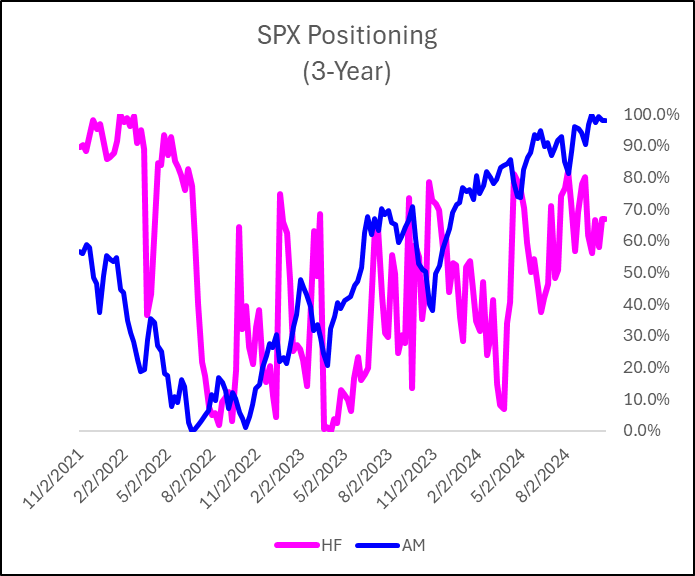
In short, we think investors should remain long risk assets (equities, commodities, high yield) with a preference for USD vs. g10 and EM. Fixed income allocations should aim to balance duration with yield, though with spreads being so narrow, a cash (CD/MM) position remains competitive. The economy is fluctuating between a “mid cycle” and “late cycle” environment, while risk assets are trading “early cycle”. With positioning near the max, this means that expectations are quite high and we don’t recommend extending risk in this environment.
Beyond the election, this week we have an FOMC meeting with a press release and conference on Thursday. We expect a 25bp cut given the language in the beige book, okay-ish wage data (mixed), soft payrolls, and still depressed manufacturing PMI. The Fed remains on track to deliver 100bp of cuts this year (25bp this week, another 25bp in December).
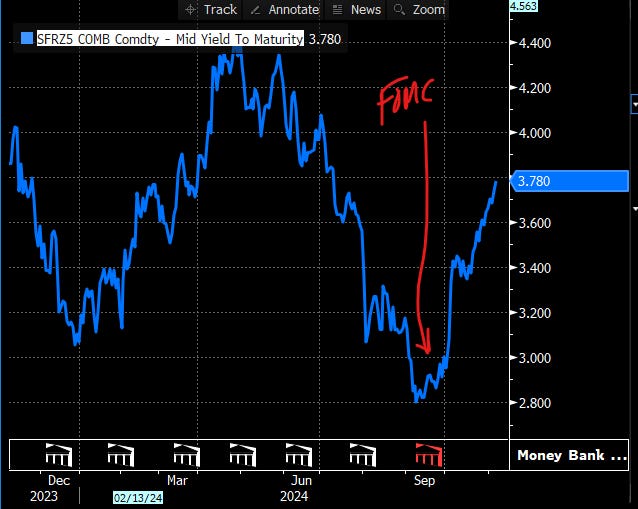
The market expects 1.7 cuts this year — 98% chance of a cut is priced in for November while just under a 70% chance is for December. We have not seen any data that would counter that path. However, it is possible that the Fed begins to communicate a refocus on inflation and activity. We think that shift will impact rate cuts for next year (market is pricing in 2-3) with a terminal rate over 3.7%. For comparison, the Fed pointed to 3.4% in their latest Summary of Economic Projections.
Ultimately, a weaker economic backdrop makes us think that the Fed will remain in cutting mode.
Some charts to mull over:
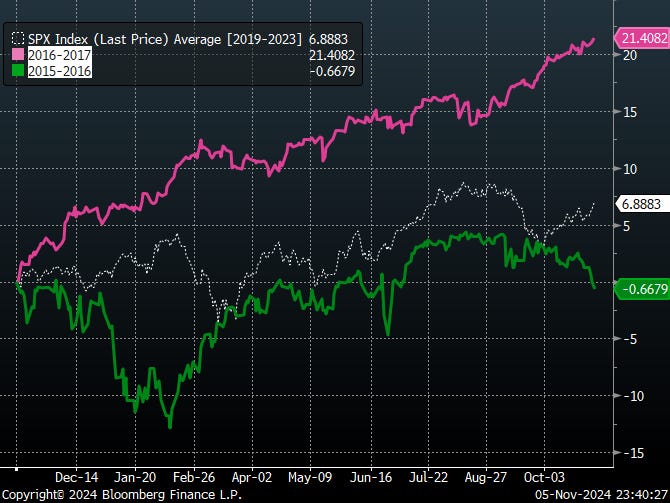
(1) Equity performance post-election tends to be strong. Below is a chart comparing Nov 2015/16 to Nov 2016/17, where a clear trend post-election took place:
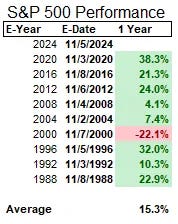
(2) In our last note, we shared this analysis suggesting subsequent 1-year performance on the S&P averaged over 15%:
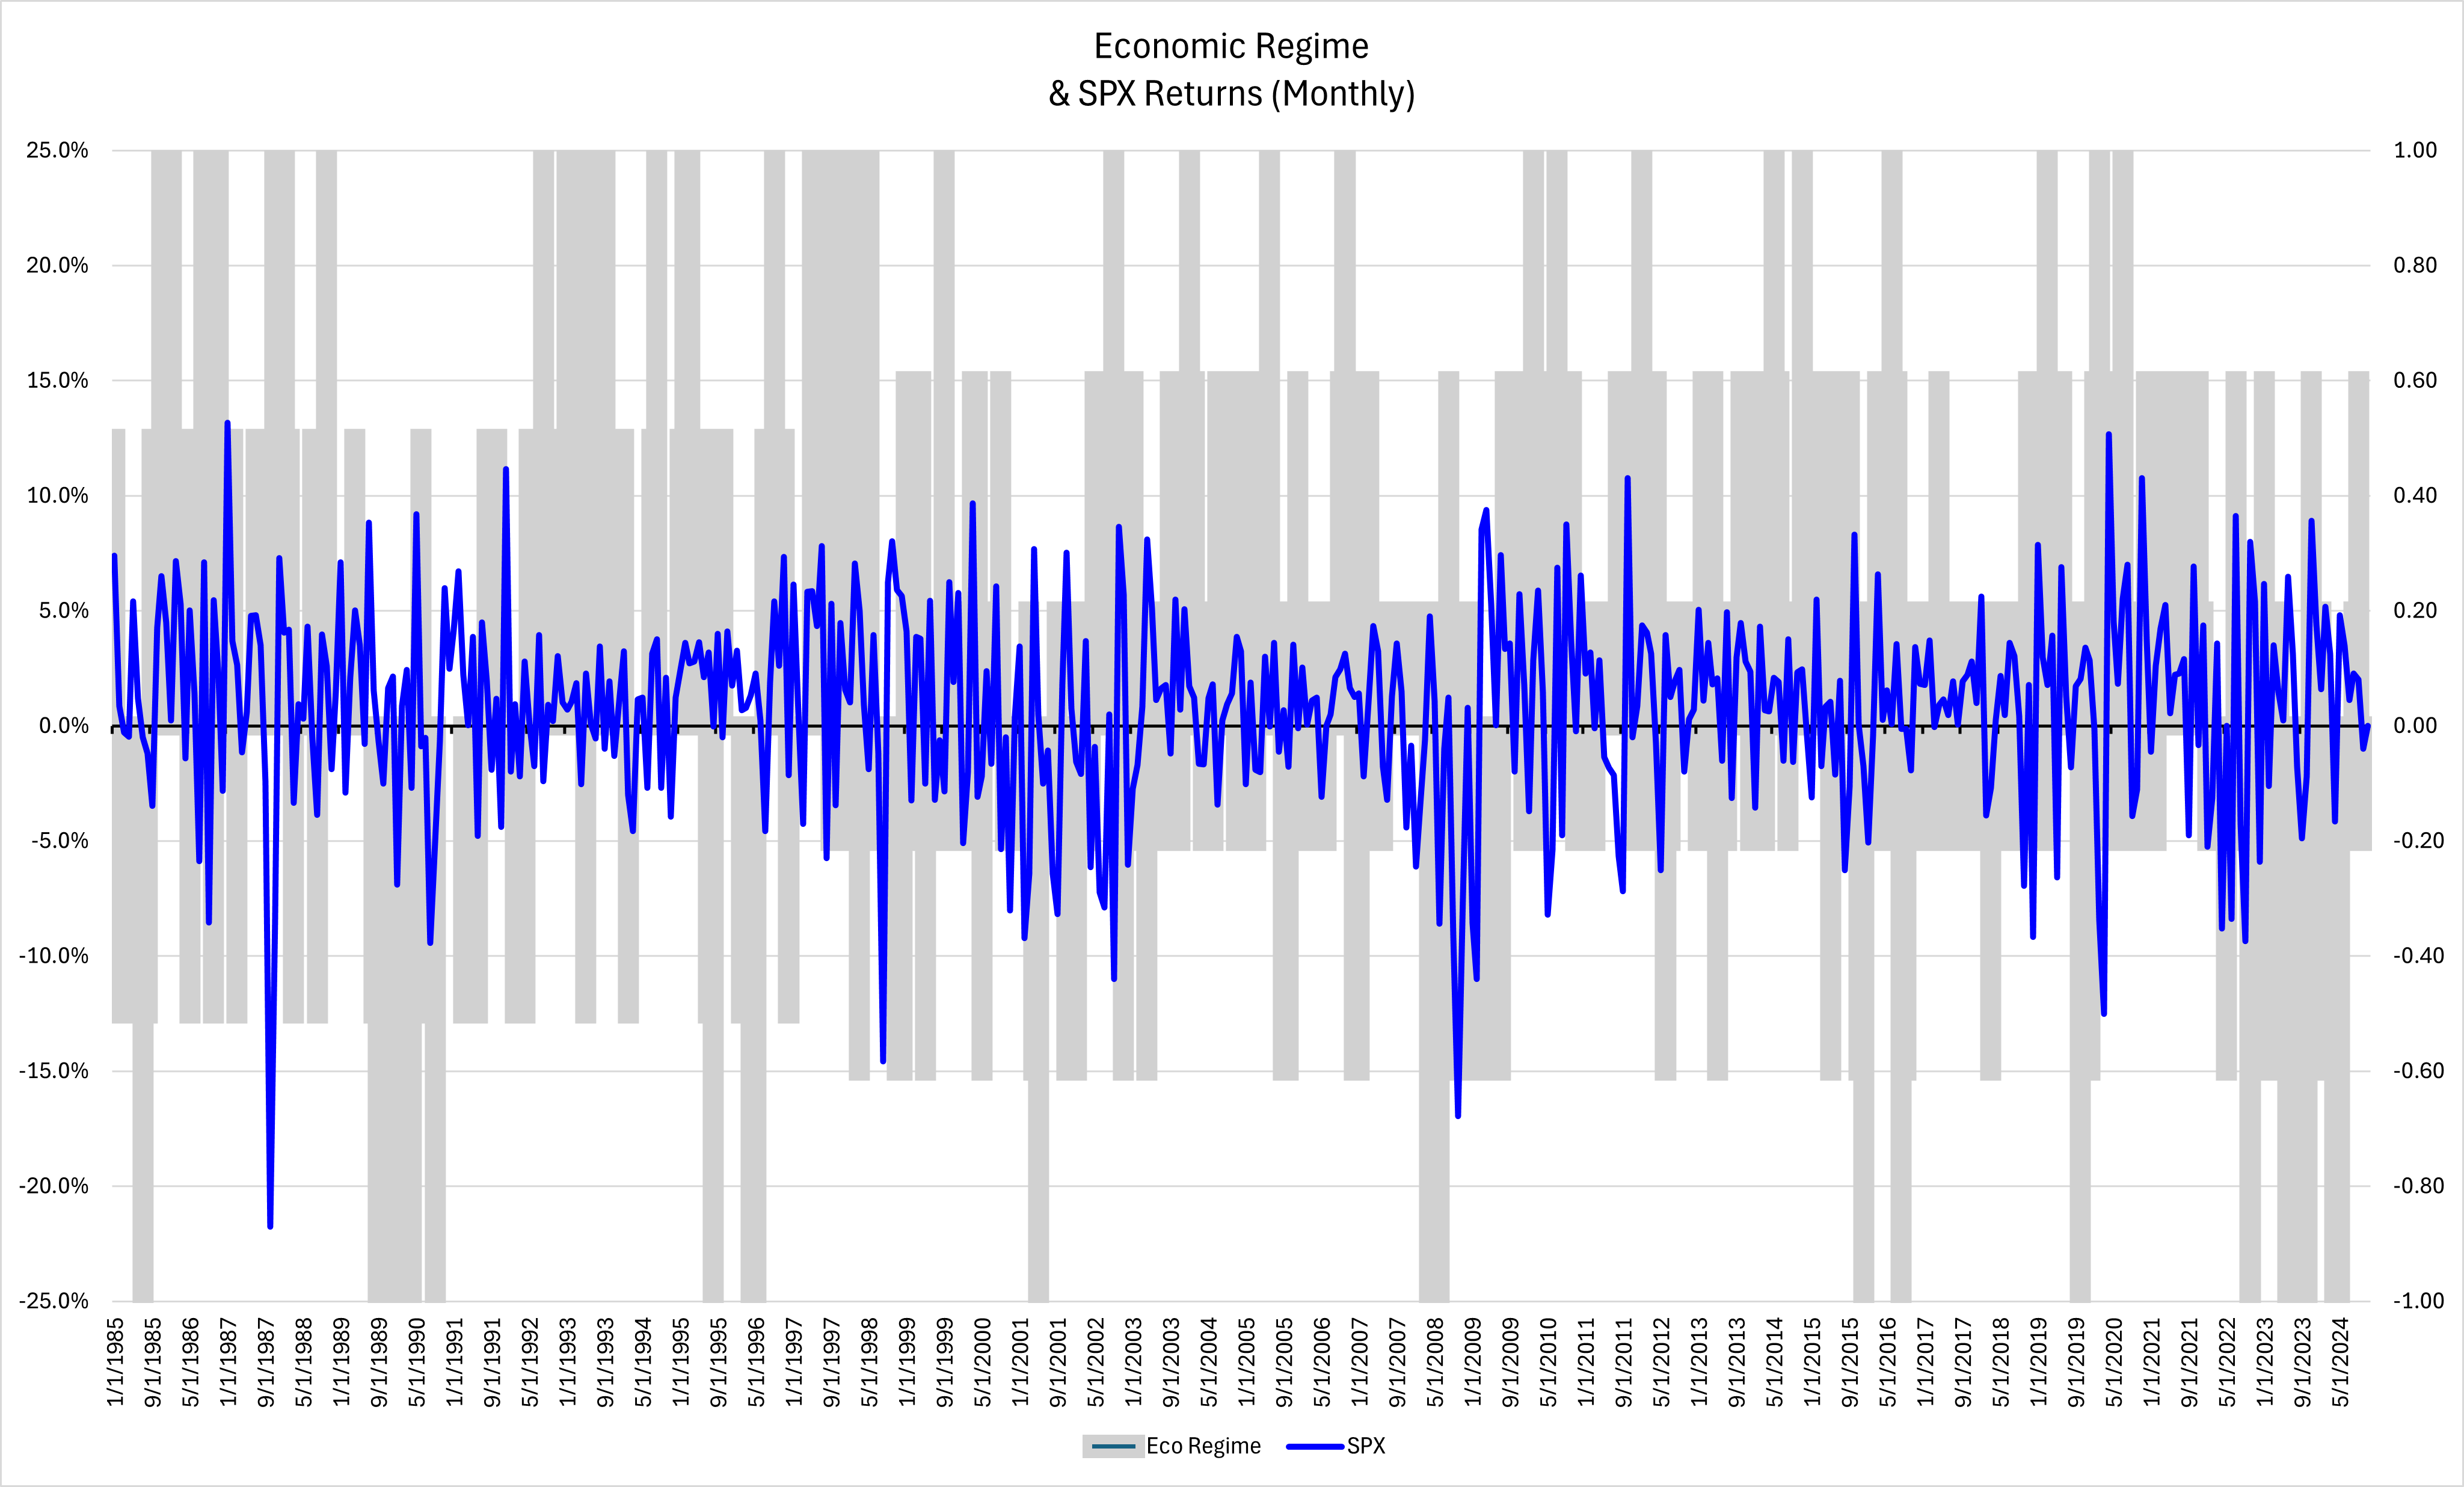
(3) However, our economic regime model (Change in ISM, New Orders, Unemployment Rate, 2Yr Yield, and 10Yr Yield) points to a weaker backdrop vs the economy in 2016-2017:
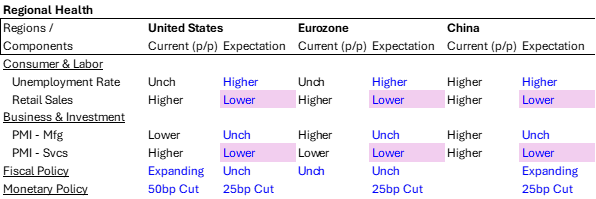
(4) Current regional health views:
(5) Futures positioning remains elevated as of the last COT report:
(6) The Treasury Sell Off:
(7) The Hawkish 50bp cut:
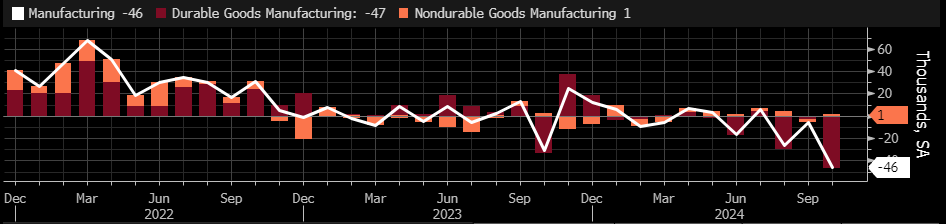
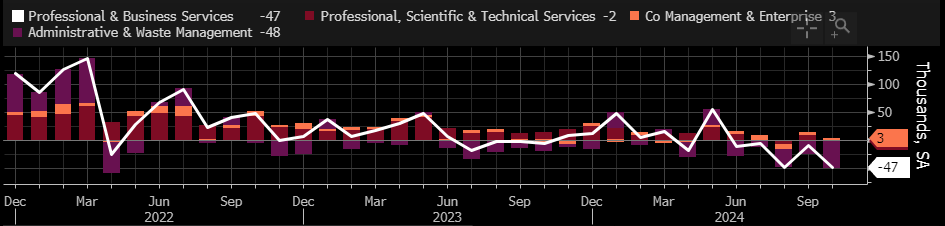
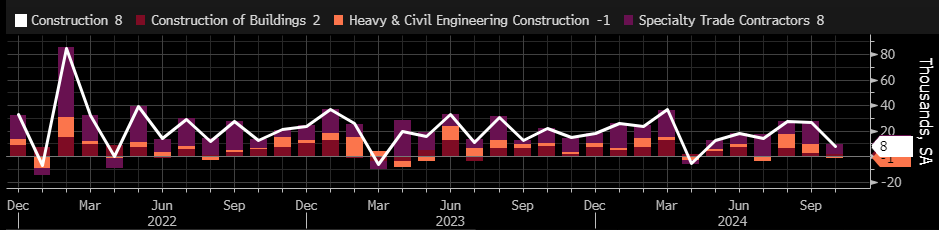
(8) Weakness in Auto manufacturing employment, Temp & Professional, and Construction employment are sensitive to interest rates and economic activity — we think they have further to decline.
Note on the election — regardless of who you voted for, I wish our new President the best of luck and hope we can come together to work towards building a more prosperous and free country.
Sincerely,
Muhammad Wahdy
Portfolio Manager
Wahdy Capital